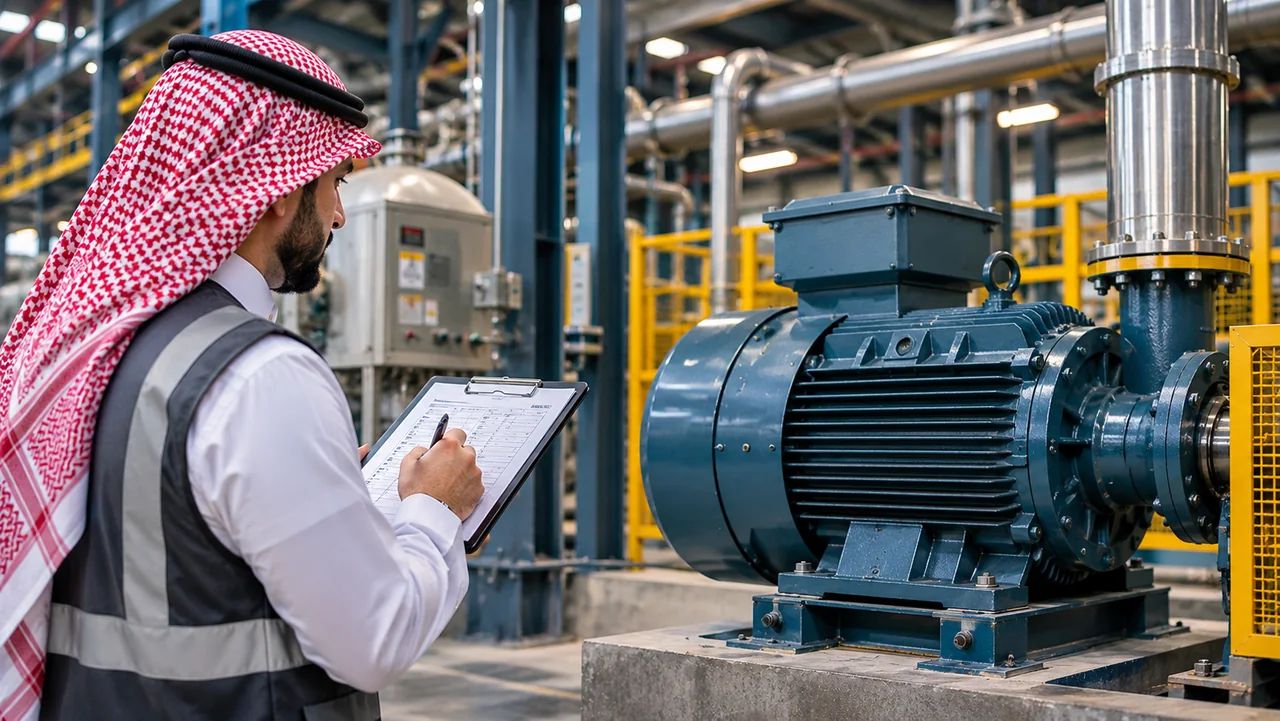
Machinery and production equipment can account for a substantial part of an industrial business's invested capital. Yet original acquisition cost is rarely a complete guide to present value. Equipment changes through use, maintenance, technological progress and market conditions. A sound valuation therefore combines a technical understanding of the asset with evidence about its economic environment.
Defining the subject assets
The scope may include individual machines, production lines, industrial installations, workshop equipment or other movable assets. The context matters. A machine that can be removed and sold on its own raises different considerations from an integrated production system whose dismantling and reinstallation require substantial work. The valuation should also establish whether related land, buildings or business interests are excluded.
Why the purpose matters
Equipment may need to be valued for financing, purchase, disposal, insurance, liquidation, restructuring or financial reporting. The assumed circumstances can differ across those purposes. An assessment of equipment remaining installed and operating should not automatically be used as if it represented the value achievable under a rapid disposal scenario.
Technical information and inspection
Helpful information includes asset registers, make and model, serial number, production capacity, year of manufacture, hours of use, maintenance records and modifications. An inspection can support the description and understanding of condition within the engagement's scope. It should not be mistaken for a comprehensive performance, safety or engineering certification unless those examinations are separately specified.
Physical and functional deterioration
Physical wear reflects use, age, maintenance and environment. Functional obsolescence arises when a newer design or process delivers a similar function more efficiently. Economic obsolescence may be external to the machine itself, for example when demand for its output falls or changes in the industry reduce its usefulness. Different types of obsolescence should not be collapsed into a single arbitrary annual deduction.
Using market evidence
The market approach relies on information about comparable equipment, with adjustments where justified for differences such as model, condition, age, location and transaction circumstances. For highly specialized assets, directly comparable sales may be scarce. The absence of close comparables is a limitation to be addressed, not a reason to force unrelated market prices into the analysis.
Considering replacement cost
The cost approach may consider the cost of obtaining a modern equivalent that provides comparable utility and then account for depreciation and relevant forms of obsolescence. This is not the same as using the historical purchase price less a fixed percentage for each year. The likely remaining economic use, replacement technology and actual condition can all affect the outcome.
When income analysis is relevant
An income approach may be appropriate if benefits attributable to the assets can be identified with sufficient reliability. Care is needed where revenue is generated by a whole operation involving property, labor, management, goodwill and several connected machines. Attribution of all business income to one asset would create a misleading result.
Communicating the conclusion
A valuation should identify the assets, basis and effective date of value, intended use, selected methods, inputs, material assumptions and limitations. Whether an asset is operating, idle, difficult to relocate or subject to uncertain demand can be crucial to understanding the conclusion.
Does value change when equipment stays in place?
It can. Machinery assumed to continue operating where it is installed may be assessed under different conditions from equipment requiring dismantling and removal. Transport, reassembly, commissioning and the size of the potential buyer market can all influence the analysis. The assumptions must be consistent with the engagement's intended purpose.
Software and control systems
Modern equipment often relies on control software, specialist licenses and maintenance agreements. It is important to determine whether such rights and accessories are included in the assets being valued. The price of a machine should not be assumed to include every associated license or piece of intellectual property.
Why book values differ
Accounting carrying amounts reflect the relevant measurement and depreciation policies. Professional valuation answers a question under a specific basis and date, using the asset's circumstances and economic evidence. A fully depreciated machine may remain serviceable, while a newer one may be affected by rapid technological obsolescence. Understanding each figure's purpose is essential before comparing them.
The importance of asset registers
A well-maintained equipment list records clear descriptions, technical specifications, identifiers, location and operating status. In large facilities, reconciling the asset list with actual equipment may be an important part of gathering evidence. Unclear descriptions or duplicate asset names should be addressed before unreliable comparisons are allowed to shape a conclusion.
Machinery and equipment valuation helps organizations look beyond the book value or initial cost of their assets and make financing, disposal and investment decisions with a clearer understanding of the evidence involved.