Understanding the inventory
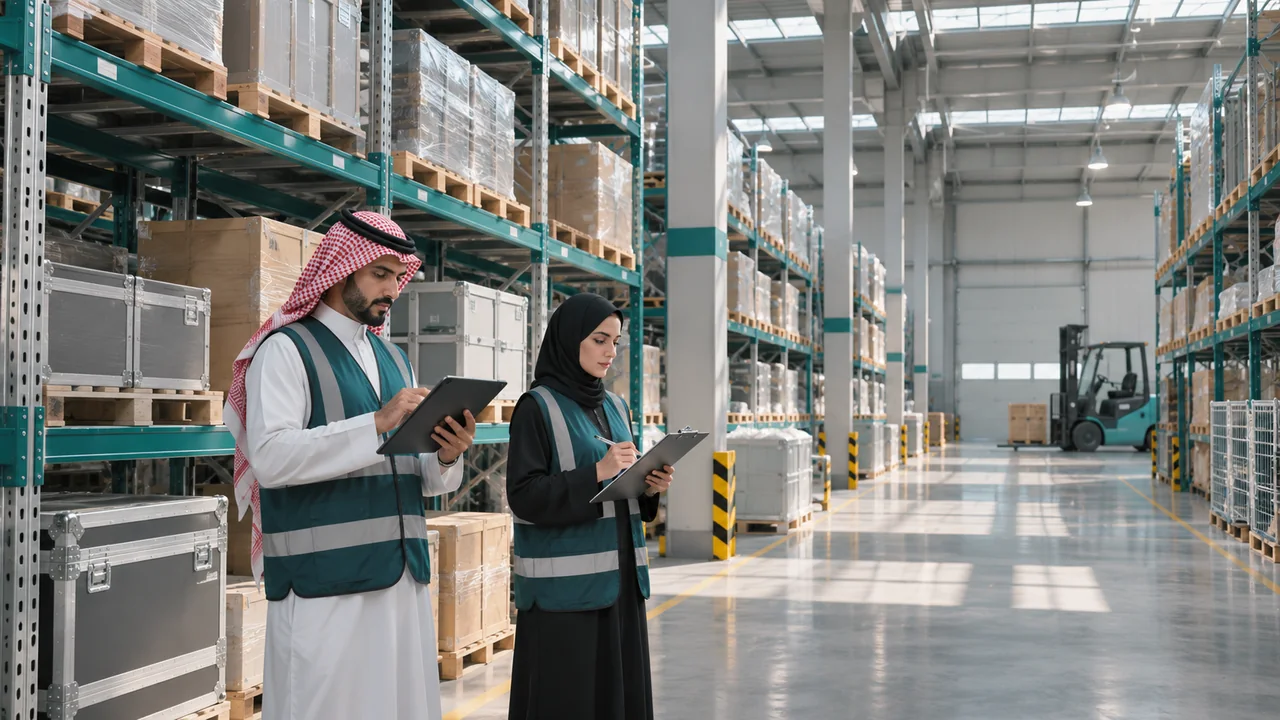
The scope may cover commercial merchandise, industrial materials, manufactured items or a defined group of spare parts. Reliable records are important: descriptions, quantities, location, condition, age and movement history can help identify what is actually being assessed. Items that are obsolete or damaged should not be considered equivalent to active, saleable stock merely because their recorded purchase costs are similar.
Stocktaking and valuation are different tasks
Stocktaking asks what exists and how much of it is present. Valuation asks what that inventory is worth under a defined basis at a specified date and for a particular purpose. Physical verification may contribute to the evidence used in valuation, but it is not a substitute for analyzing condition, demand, cost information and circumstances affecting value.
Different objectives require care
A business may seek an inventory valuation for a financing decision, disposal, restructuring, liquidation, financial reporting or internal analysis. The professional valuation basis appropriate to an engagement should not be confused with a particular accounting cost-flow formula or routine stock pricing method. The purpose must be clear before choosing the analysis.
Factors that shape the outcome
Product condition, shelf life, technological changes, slow-moving categories, sales prospects and the costs necessary to complete or dispose of an item may all matter. Some specialist parts have substantial operational usefulness within a facility but limited demand in a wider resale market. Such distinctions may be material to the value conclusion and should be explained.
A clearer view of stock
Slow-moving and obsolete stock
Goods can remain on a stock list long after demand has faded, specifications have changed or superior alternatives have entered the market. Recorded acquisition cost does not prove that the items could be sold for that amount. An informed analysis distinguishes active stock from slow-moving, obsolete or damaged categories using evidence relevant to the valuation purpose.
Work in progress
Incomplete products should not be treated as finished saleable goods. Further materials, labor, time and operational risk may be required before they can be sold. Their value can depend on the likelihood and cost of completion and on the circumstances assumed in the engagement.
The valuation date matters
Material prices and demand may change quickly in some industries. A valuation should therefore refer to an effective date rather than presenting value as permanently fixed. Material later developments may require updated information before a new business decision is made.
A credible result requires sensible classification, relevant data, explicit assumptions and transparent reasoning. Our inventory valuation service addresses commercial and industrial stock in a way that helps organizations see beyond recorded quantities and interpret the information required for business decisions.