A company may hold buildings, machinery, vehicles and equipment across several sites and still lack a reliable picture of what it owns. The problem is often not the absence of assets, but the absence of consistent information: where is each item, who is responsible for it, is it still in use and what value is relevant to the decision being made? Answering these questions requires more than a single spreadsheet.
What is a fixed asset?
In a general financial reporting context, tangible fixed assets include resources held for production, service delivery or administrative use over more than one period, subject to the applicable accounting standards. Classification depends on the nature and use of the item. Inventory held for sale is not the same type of asset as the machinery used to manufacture that inventory.
Asset identification and listing
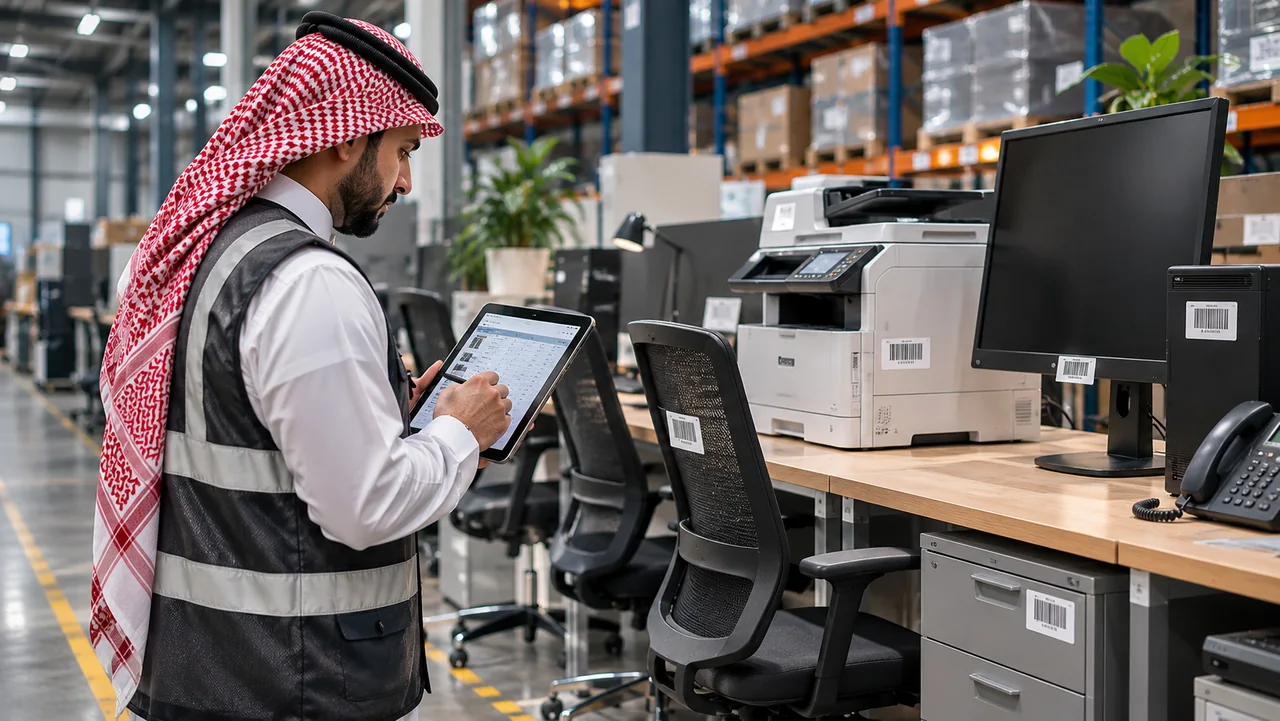
The identification stage establishes an organized record of assets within a defined scope. This can include descriptions, locations, tags or identifiers, responsible teams, acquisition details and condition. The objective is to create a reliable foundation for subsequent management decisions and updates.
Physical verification
Verification asks whether recorded assets actually exist in their stated locations and whether their recorded condition and assignment remain accurate. Items may have been moved, replaced, damaged or retired without the register being updated. Reconciling these differences requires investigation and documentation rather than simply changing the figures until the list appears to balance.
Tags and asset registers
A consistent identification system reduces confusion when equipment looks similar or moves between locations. Useful registers record changes in custody, maintenance and disposal as well as basic asset details. The right level of technology depends on the organization's scale, but the principles of traceability and timely maintenance of information remain important.
Valuation answers a different question
Asset valuation estimates worth under a specified basis, date and purpose. It may be needed for financing, a transaction, investment planning or financial reporting. Physical existence and historical purchase cost do not automatically establish that worth. Market conditions, equipment condition, technological obsolescence and assumptions may be material.
Accounting revaluation
Revaluation for financial reporting purposes is governed by the relevant accounting requirements, including the policies applied to asset classes, measurement and disclosure. It is not identical to obtaining an informal resale estimate. An organization should work with its accounting specialists to understand how valuation information is used under its reporting framework; a change in market price does not necessarily translate into an automatic entry under every circumstance.
How the activities connect
An organization may first identify its holdings, then conduct physical verification and later commission valuation of a selected asset class. These stages strengthen one another. A machine with incomplete specifications is harder to value, while a valuation report adds less operational usefulness if the asset register cannot establish where the machine is or who maintains it.
Better information, better choices
Reliable asset information supports maintenance planning, replacement decisions, evaluation of underused equipment and investment priorities. Distinguishing book value, market value and operational usefulness also avoids asking a single number to answer several different questions.
Why finance and operations records differ
Accounting teams may focus on acquisition cost, classification and depreciation, while operations teams need information about an asset's location, condition and performance. These systems need not hold identical fields, but they should identify the same assets consistently. Inconsistent descriptions and missing identifiers make physical checks and valuations more difficult.
When value needs another look
Changes in market conditions, asset utilization or a business reorganization may trigger a need to reassess value-related information. Yet a commissioned valuation is not necessarily the same exercise as an impairment test or an accounting revaluation. The question being asked should determine the professional work and documentation required.
Common recordkeeping errors
Frequent problems include failing to update an asset's location, not recording disposal, grouping different machines under one identifier and treating book value as the expected selling price. Clear responsibilities and regular updates often improve data reliability before an organization invests in more complex asset systems.
Good information needs accountability
When responsibility for record updates is unclear, transfers, maintenance and disposals may go unrecorded. Assigning ownership of the register, establishing review intervals and documenting material changes can reduce those gaps. Simple administrative disciplines often have a significant effect on the reliability of later verification, valuation and business decisions.
The goal is not to create more paperwork. It is to maintain a trustworthy picture of the organization's physical resources and use that understanding when decisions about those resources are required.